

Get Paid Early: Cash Advance analysis by Appwee
Getting paid before payday sounds simple, but the practical experience depends on more than pressing a button. I spent time with Get Paid Early: Cash Advance to see how it fits into the everyday gap between earning money and having access to it. StreamFunds, Inc. positions it as a finance app for accessing earned pay early rather than taking a conventional loan, and that distinction shapes the whole experience.
The app is free to download and aimed at Everyone, with a straightforward promise: help users reach money they have already earned, without interest or hidden fees. That makes it appealing when a bill, grocery trip, or transport cost arrives before payday. At the same time, early access is not the same as extra income. In my view, the app is most useful as a carefully managed timing tool, not as a permanent replacement for budgeting or a full banking service.
How Get Paid Early: Cash Advance fits real financial routines
The first thing I noticed is that the value of this app appears during a narrow but very familiar moment: the money exists in your pay cycle, yet it is not available in your account when you need it. A regular bank transfer may force you to wait. A credit card may create a balance that lasts beyond payday. A traditional loan can add interest and paperwork. Early-pay access sits between those choices, offering convenience while still requiring discipline.
A realistic example is a worker who has several days left before payday but needs to replace a flat tire to get to work. Using a credit card may be easy, but it can turn an urgent repair into a longer repayment problem. A paycheck advance can solve the immediate timing issue, provided the user understands that the next paycheck will be smaller or otherwise affected by the advance. That trade-off is easy to overlook when the need feels urgent.
I would not treat the app as free money, even though the app itself costs nothing to download and its central message emphasizes no loans, no interest, and no hidden fees. The responsible question is not simply, “Can I get money now?” It is, “Will receiving part of my earned pay early leave enough for rent, food, transport, and other commitments later?” That second question should guide every decision inside the app.
StreamFunds, Inc. has kept the product focused on a single financial problem rather than trying to become a complete money-management suite. That focus is useful for someone who wants a direct route to early pay. It is less suitable for a person looking for investing tools, detailed spending analysis, bill negotiation, or broad banking features. I found the narrow purpose easier to understand, but it also means the app cannot replace the wider financial picture many users need.
What the current app tells me about its maturity
The current release is version 3.0.39, and the app has passed the early experimental stage in practical terms. It has more than fifty thousand installs, an average rating of 4.2, and several hundred ratings overall. Those figures suggest that people are finding a reason to try it, while the rating also hints that the experience will not be equally smooth for everyone.
I pay attention to that balance because finance apps are judged differently from entertainment apps. A small delay, an unclear eligibility step, or a connection problem can matter much more when someone is trying to cover an immediate expense. The number of ratings is not a guarantee of approval or speed, so I would still approach the first use as a setup process rather than assuming the app will solve an emergency instantly.
The minimum operating-system requirement is Android 7.0, which makes the app accessible to many older Android phones. That is a practical advantage for people who do not replace their device frequently. It also means that phone age alone should not automatically prevent someone from trying it, although the quality of the experience will still depend on the device, the operating system’s condition, and the user’s network connection.
Why connectivity matters more here than in ordinary finance apps
With an app that deals with earned pay, connectivity is part of the experience rather than a minor convenience. The user may need to open the app at a specific moment, review available information, move through an account-related process, and wait for a response from an online service. If the connection is weak, the frustrating part is not merely a slow screen. Uncertainty can make the user wonder whether a request was submitted, whether a step failed, or whether trying again could create a duplicate action.
I recommend using the app when the phone has a stable mobile-data or Wi-Fi connection, especially when reviewing an advance or completing an important confirmation. A brief signal may be enough to open a page, but that does not mean it is reliable enough for a financial action. I would avoid starting the process in an underground station, a crowded event, or a moving vehicle where the connection changes repeatedly.
This is also why I would not wait until the last possible minute. If the money is needed for a scheduled payment, opening the app earlier gives you time to read the result, check your account, and decide what to do if the process does not complete as expected. The app may be designed for speed, but a user should still build in time for network interruptions and normal verification steps.
One useful habit is to take note of the last screen you clearly completed before closing the app. If the connection drops, that memory helps you avoid repeating a step unnecessarily. I would also check the account or transaction history through the appropriate financial channel before assuming that a failed-looking screen means nothing happened. That is not a criticism unique to this product; it is a sensible precaution whenever an online finance action is interrupted.
Using it in the places people actually need it
The strongest mobile use case is a short, deliberate session at home or somewhere with dependable reception. I found that this kind of app works best when I am not multitasking. Trying to handle an advance while shopping, rushing between appointments, or answering messages creates more room for mistakes, particularly when the user needs to compare the available amount with upcoming expenses.
There is a difference between portability and convenience. Having access from a phone means the user does not need to sit at a desktop computer, which is valuable when an unexpected expense appears away from home. But mobile access can also encourage impulsive decisions. A large screen makes it easier to review dates, balances, and consequences side by side; on a phone, users may skim and tap quickly. I suggest slowing down at the confirmation stage, even if the rest of the app feels fast.
For someone paid on a predictable schedule, a good workflow is to check the app only when a real short-term need exists. I would not repeatedly open it throughout the day hoping the available amount changes. That habit turns a focused tool into a source of financial temptation. A better approach is to identify the expense, calculate what must remain for the next pay period, and then use the app only if the numbers still make sense.
People with older phones may appreciate the modest operating-system requirement, but they should keep enough storage and system stability for any finance app to function normally. A phone that frequently closes apps, loses background connectivity, or struggles with account sign-in can make the experience feel unreliable even when the service itself is operating normally. Updating the phone where practical and restarting it before an important session can remove simple technical friction.
I also prefer using a private connection for financial activity. Public networks can be crowded and unpredictable, and a weak public connection adds both delay and distraction. If the only available option is poor reception, waiting until a safer, steadier connection is available is usually wiser than rushing through a money-related decision.
What to do when a request or screen does not go as planned
Failure recovery is where my opinion becomes more cautious. A finance app can feel excellent when everything works and stressful when a page hangs at the exact moment the user needs clarity. The most important response is to avoid pressing the same confirmation repeatedly. First, wait briefly, check whether the screen changes, and then review any visible status information before trying again.
If the app closes or loses connection, reopen it and look for the current state rather than immediately starting over. The practical goal is to distinguish between an unfinished request and a completed action whose confirmation was interrupted. Keeping a note of the amount and purpose of the request can help you compare what the app shows after reopening it.
Another useful safeguard is to keep the app updated. The current version is 3.0.39, so users on an older release should check whether an update is available before blaming a connection problem on the service. Updates do not guarantee a perfect session, but staying current reduces the chance that an avoidable software issue complicates an urgent financial task.
I would also separate technical failure from eligibility disappointment. If the app does not provide the result a user hoped for, that does not necessarily mean the phone, connection, or installation is broken. Repeatedly reinstalling the app will not turn an unsuitable financial situation into a suitable one. In that case, the better response is to review the available options calmly and avoid replacing an early-pay request with a more expensive alternative simply because the first attempt was frustrating.
For urgent needs, I recommend keeping a backup plan that does not depend entirely on one app. That might mean knowing which bill can be moved, which expense can wait, or whom to contact before a due date. This is especially important because a phone-based service is still dependent on account access, network availability, and successful processing. Portability is valuable, but it should not be confused with guaranteed immediate access.
Being careful with data, permissions, and financial expectations
Any app connected to earned pay deserves a more careful approach than a casual download. Before using it, I would read each screen instead of tapping through automatically, particularly where the app explains account connections, identity checks, repayment timing, or the effect of receiving pay early. The store summary makes the no-interest and no-hidden-fee position clear, but users should still understand the exact mechanics presented during their own setup.
Data-conscious use starts with installing the app from the legitimate Android store and keeping the phone protected with a screen lock. I would avoid sharing account credentials through messages or entering them while someone else is watching. If the app requests access related to employment or banking, I would examine the wording and purpose carefully before agreeing. Financial convenience is not a reason to abandon ordinary security habits.
Notifications deserve attention too. A user may want reminders about an important status, but financial notifications can reveal sensitive information on a locked screen. Adjusting the phone’s notification preview settings is a small step that can prevent other people from seeing balances or payment-related messages. This is one of those details that does not appear in a short store description but matters in everyday use.
I would also avoid using an unsecured shared device. A personal phone with a current lock method gives the user more control over session history and notifications. After finishing, signing out when appropriate and closing the app is sensible, especially if the phone is sometimes borrowed. The aim is not paranoia; it is reducing the number of places where a financial session can be exposed.
The biggest data-related trade-off is convenience versus visibility. A service that knows enough about a user’s pay situation can make early access practical, but the user should remain aware of what is being connected and why. If you are uncomfortable linking the necessary financial information, this may not be the right product for you. A slower manual budgeting method could be preferable to using a service whose data relationship you do not understand.
Who should use it, and who should look elsewhere?
I see the best fit in workers with regular earned pay who occasionally face a timing mismatch between an expense and payday. The app can be particularly useful when the alternative is a high-cost borrowing option or a late payment. Its free price and Everyone age rating make the initial barrier low, while the focused purpose keeps the idea easy to grasp.
It is less appropriate for someone who routinely needs an advance every pay cycle just to cover ordinary living costs. In that situation, early access may hide a recurring budget shortfall rather than solve it. A conversation with a financial counselor, a revised spending plan, or a more suitable bank account could address the underlying problem better. I would also be cautious if your income changes frequently, because planning around an expected amount can become difficult.
Compared with a credit card, the appeal is avoiding a revolving balance and interest-based borrowing. Compared with a conventional personal loan, the process is aimed at a much smaller timing problem rather than a long repayment period. Compared with overdraft protection, it may feel more intentional because the user chooses to access earned pay instead of simply letting a transaction push an account below zero. Each alternative has different conditions, so the cheapest-looking option is not automatically the best one for every situation.
A normal savings account remains better when the expense can wait. Savings provide a buffer without reducing a future paycheck, and they remove the need to make a rapid decision during a stressful moment. I would use this app before a costly emergency borrowing option, but after checking whether savings, a flexible bill date, or a trusted personal arrangement can solve the problem with less disruption.
My verdict on the connected mobile experience
After reviewing how the app fits into real mobile use, I think Get Paid Early: Cash Advance is most convincing as a focused bridge between work completed and payday arrival. It is free, clearly positioned in the finance category, and supported by a meaningful user base. The 4.2 average rating suggests a generally positive reception without implying that every user will have the same result.
Its biggest strength is the clarity of the problem it addresses. When the issue is timing rather than a lack of income, early-pay access can be more sensible than borrowing through a credit card or loan. Its biggest weakness is the same focus: it does not remove the need for budgeting, and mobile convenience can make a serious financial decision feel too casual.
Connectivity shapes the experience at every important point. A stable connection makes checking information and completing a request more comfortable, while weak reception can create uncertainty at exactly the wrong time. I recommend using it deliberately, on a secure and dependable connection, with enough time to verify what happened rather than assuming that a loading screen tells the whole story.
My final recommendation is conditional but positive. If you have predictable pay, understand that early access changes the timing of your next paycheck, and need a practical way to handle an occasional short gap, this app is worth considering. If you need recurring financial rescue, want a full banking or budgeting platform, or are uncomfortable with the data and connectivity involved, a different solution will serve you better. Used with that perspective, StreamFunds, Inc.’s app can be a useful mobile tool rather than a habit that quietly creates a new problem.
Gallery
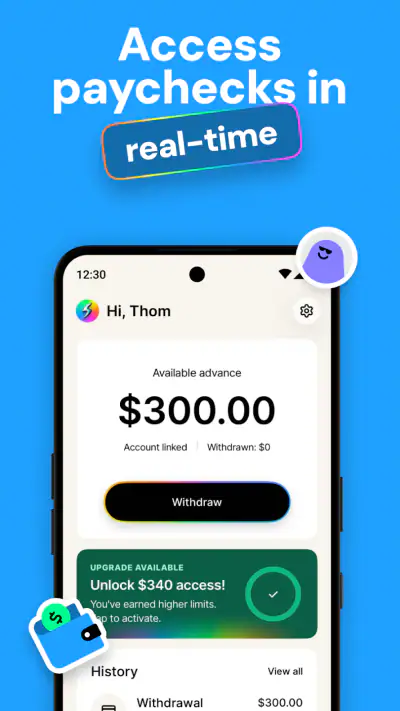
Get Paid Early: Cash Advance Pros and Cons
- Fast access to part of your earned wages before payday.
- Simple application process with clear eligibility requirements.
- No traditional credit check required for most advance requests.
- Useful for covering unexpected bills or short-term cash gaps.
- Repayment is generally automated from your linked paycheck.
- Advance limits may be low for new or infrequent users.
- Tips or optional fees can increase the overall cost.
- Requires access to payroll or employment information.
- Availability depends on employer and supported payroll providers.
- Late or failed repayment may affect future advance access.
Get Paid Early: Cash Advance Frequently Asked Questions
What is Get Paid Early: Cash Advance?
Get Paid Early: Cash Advance is a financial app designed to help eligible users access part of their earned income before their regular payday. After connecting supported employment or income information, the app may show an available advance amount and explain the repayment terms. It is not a substitute for long-term budgeting or emergency savings, and availability can vary by user, employer, location, and account history.
How does the cash advance process work?
Typically, you create an account, verify your identity, connect the required income or employment information, and review the amount you may be eligible to receive. If you request an advance, the app presents the delivery method, estimated arrival time, and any applicable fees before confirmation. Users should read every screen carefully, especially repayment dates and authorization details, before accepting an advance.
Are there fees or other costs to use the app?
The cost depends on the advance product, delivery option, and terms shown in your account. Some services may offer a standard transfer at no cost while charging an optional fee for faster delivery, and other charges or membership conditions may apply. Before requesting money, review the complete fee disclosure in the app and confirm how much you will receive and how much may be repaid.
Who can use Get Paid Early: Cash Advance?
Eligibility is not automatically guaranteed for every applicant. You may need to meet age, residency, identity-verification, income, employment, banking, and account-history requirements. The app may also require access to a supported payroll provider or bank account. Approval, available amounts, and repayment options can change over time, so downloading the app does not ensure that an advance will be offered.
When will I receive the money, and how is it repaid?
Delivery time depends on the transfer method, your bank, weekends or holidays, verification status, and whether you choose an expedited option. Repayment is generally scheduled according to the terms displayed when you request the advance and may be collected from a linked account or future income. Make sure sufficient funds are available, because a missed repayment could lead to fees, restrictions, or other financial consequences.














